Articles › AI and deep tech
Article · AI and deep tech · 19 November 2026
Anthropic IPO: Five Facts Investors Overlook Before ANT Starts Trading
Anthropic priced 980 million shares at $83, and trading on Nasdaq is due to start today. The filing contains five facts that change how a public investor reads the deal.
By Christian Soschner, 26 years building companies
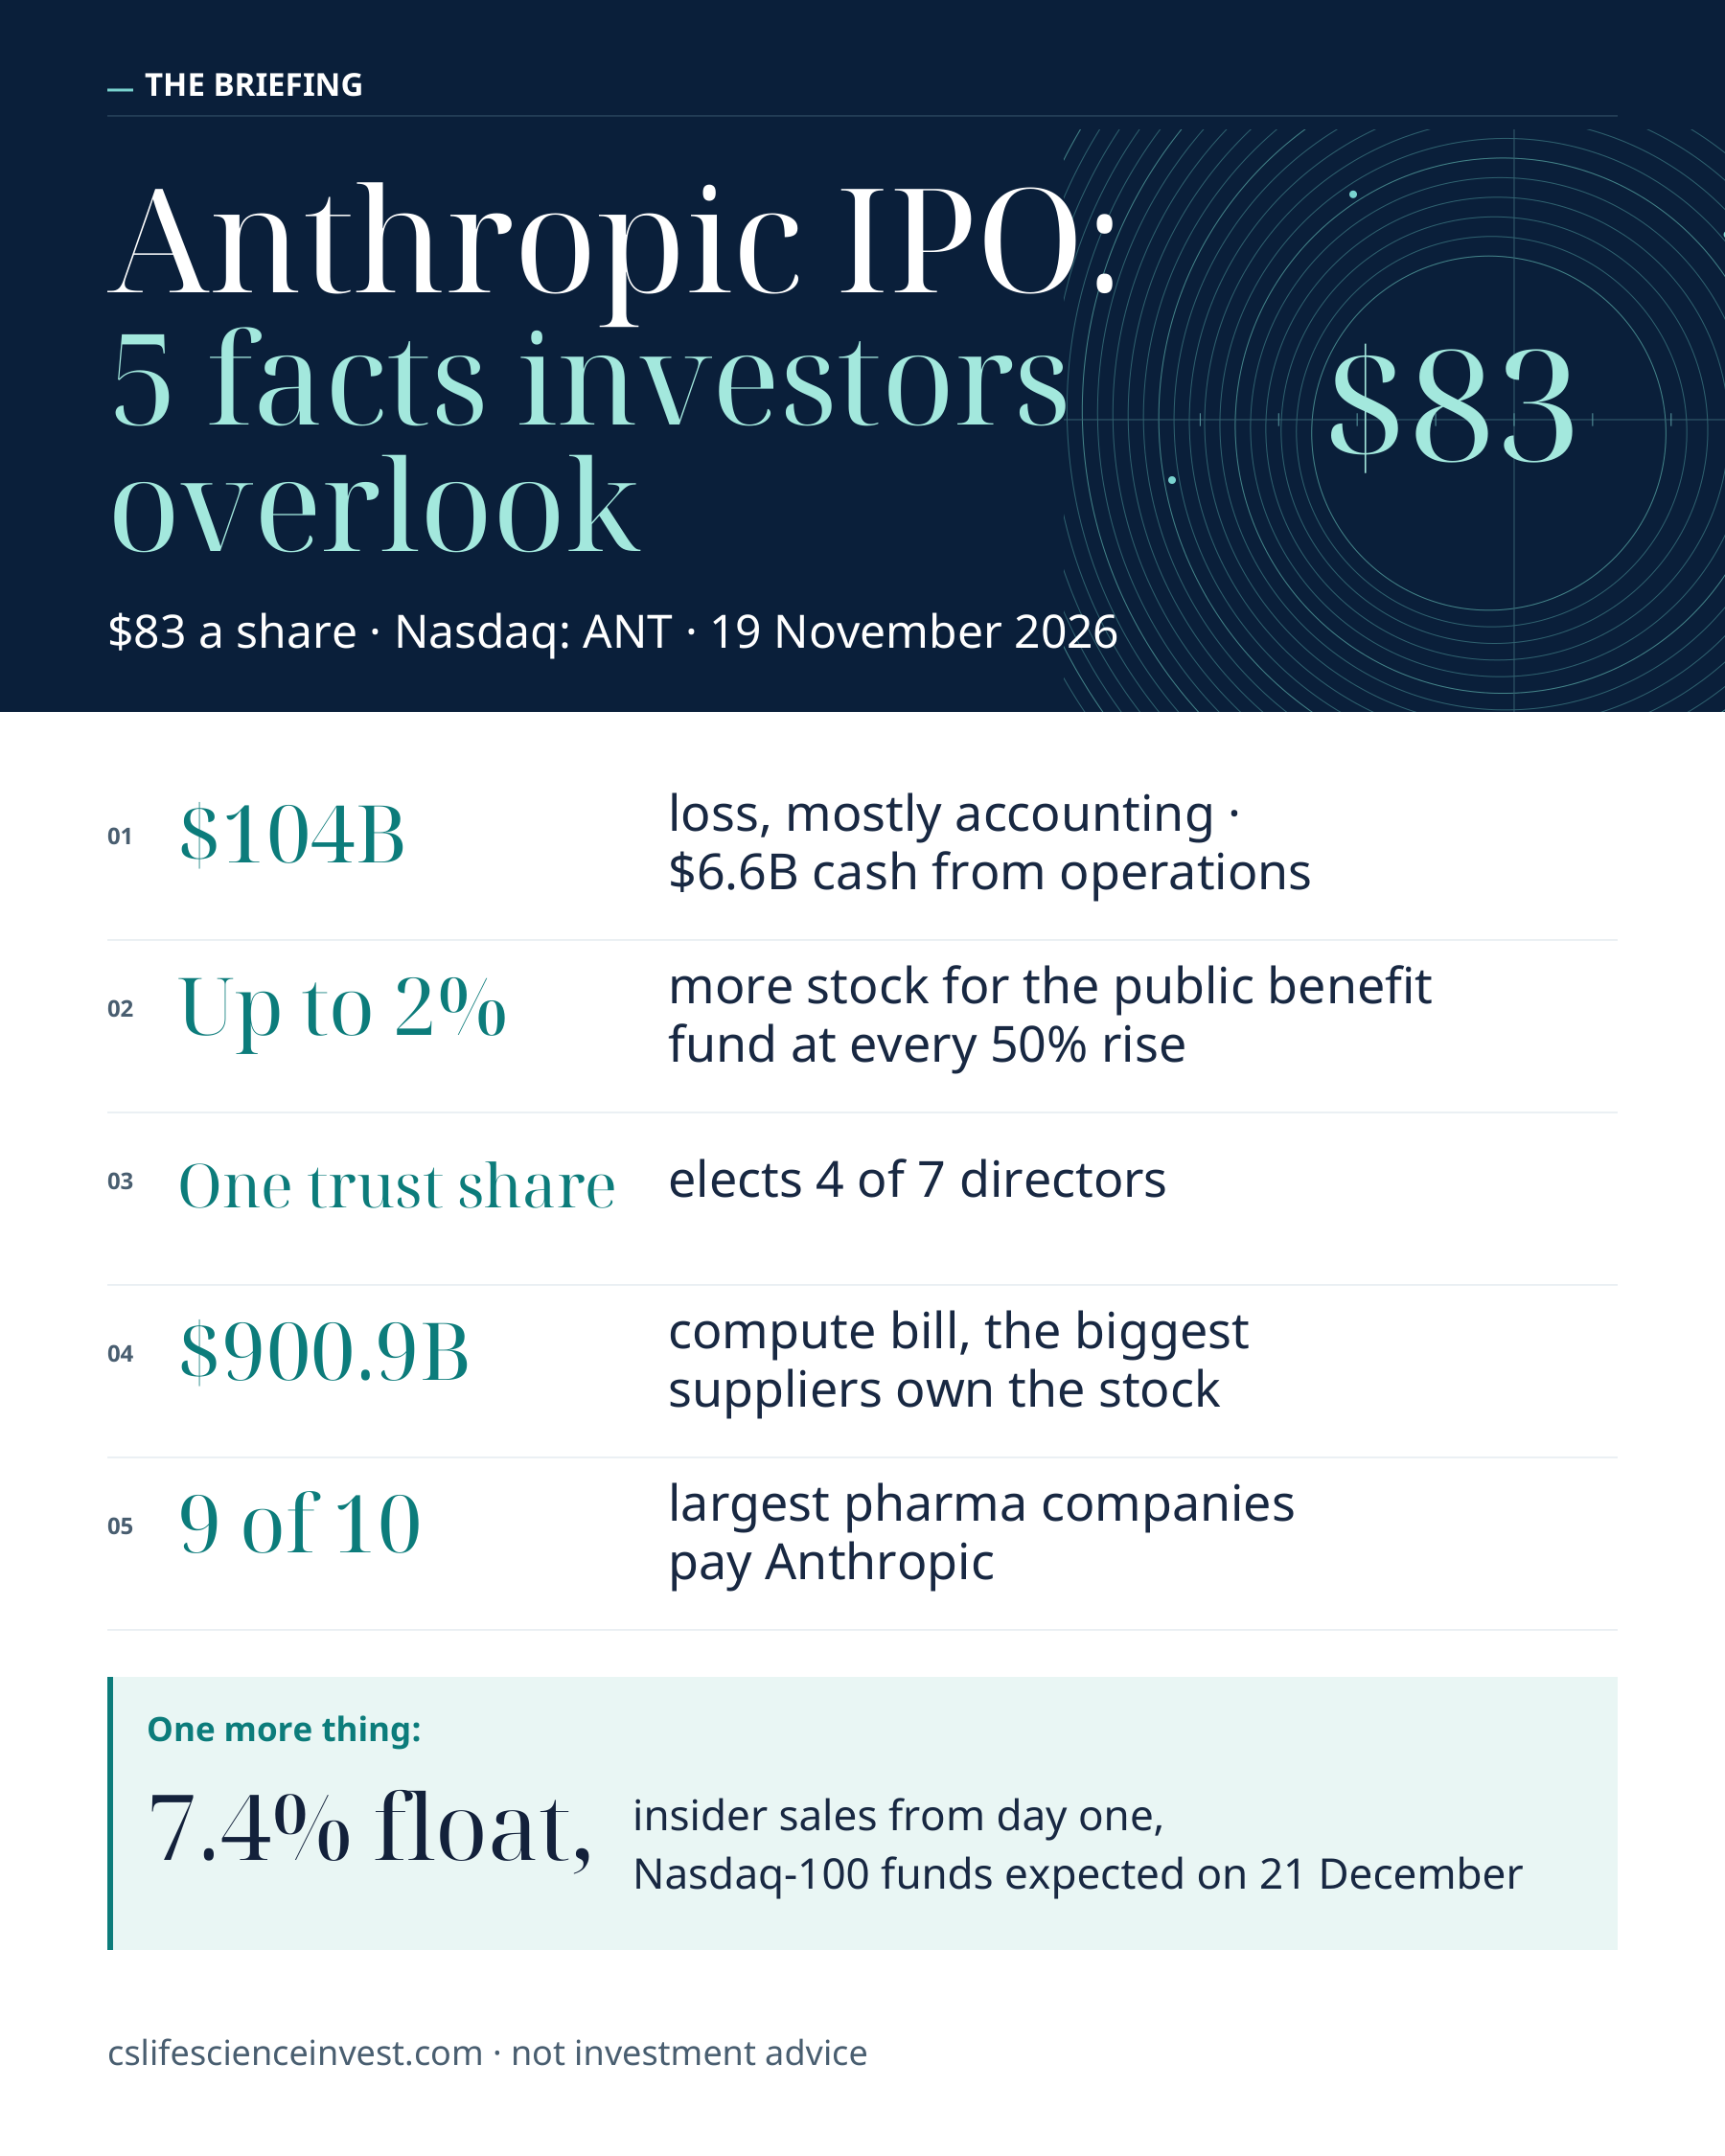
Two numbers from the same filing tell opposite stories. Anthropic lost $104 billion in the first nine months of 2026. In the same nine months, its operations brought in $6.6 billion in cash.
The offering in numbers · priced 18 November 2026
$83
price per share, above the marketed range of $70 to $78
$81.3B
base offering, ahead of SpaceX’s $75B base offering
~$1.5T
value at the IPO price, fully diluted
7.4%
of the company trades from day one
Two numbers, one filing · first nine months of 2026
−$104.0B
net loss
$94.3B revaluation of financing instruments$9.7B everything else, net
+$6.6B
cash flow from operations, after an outflow of $2.0B a year earlier
Interim figures to 30 September 2026. Source: Anthropic S-1/A.
The ticker is ANT. The price came in above the marketed range of $70 to $78. The base offering raised about $81.3 billion, more than SpaceX’s base offering of $75 billion. At the IPO price, Anthropic is worth about $1.5 trillion on a fully diluted basis. Most coverage stops at the price, the size and the record. The S-1 and its amendments tell public investors five things the headlines leave out, and one more thing that matters for the first weeks of trading.
The loss
Most of the $104 billion loss is an accounting effect. Look at the cash.
90.7%
of the net loss from one accounting line
−$1.26B
operating loss, nine months 2026
+$6.6B
cash flow from operations
About nine tenths of the loss comes from one line. Anthropic financed part of its growth with convertible notes, SAFEs and derivatives, and it chose to value its convertible notes at fair value every quarter. As Anthropic’s value climbed, those instruments gained value too, and the income statement records the difference as a $94.3 billion charge. Other items, mostly linked to partner financing, added $10.4 billion.
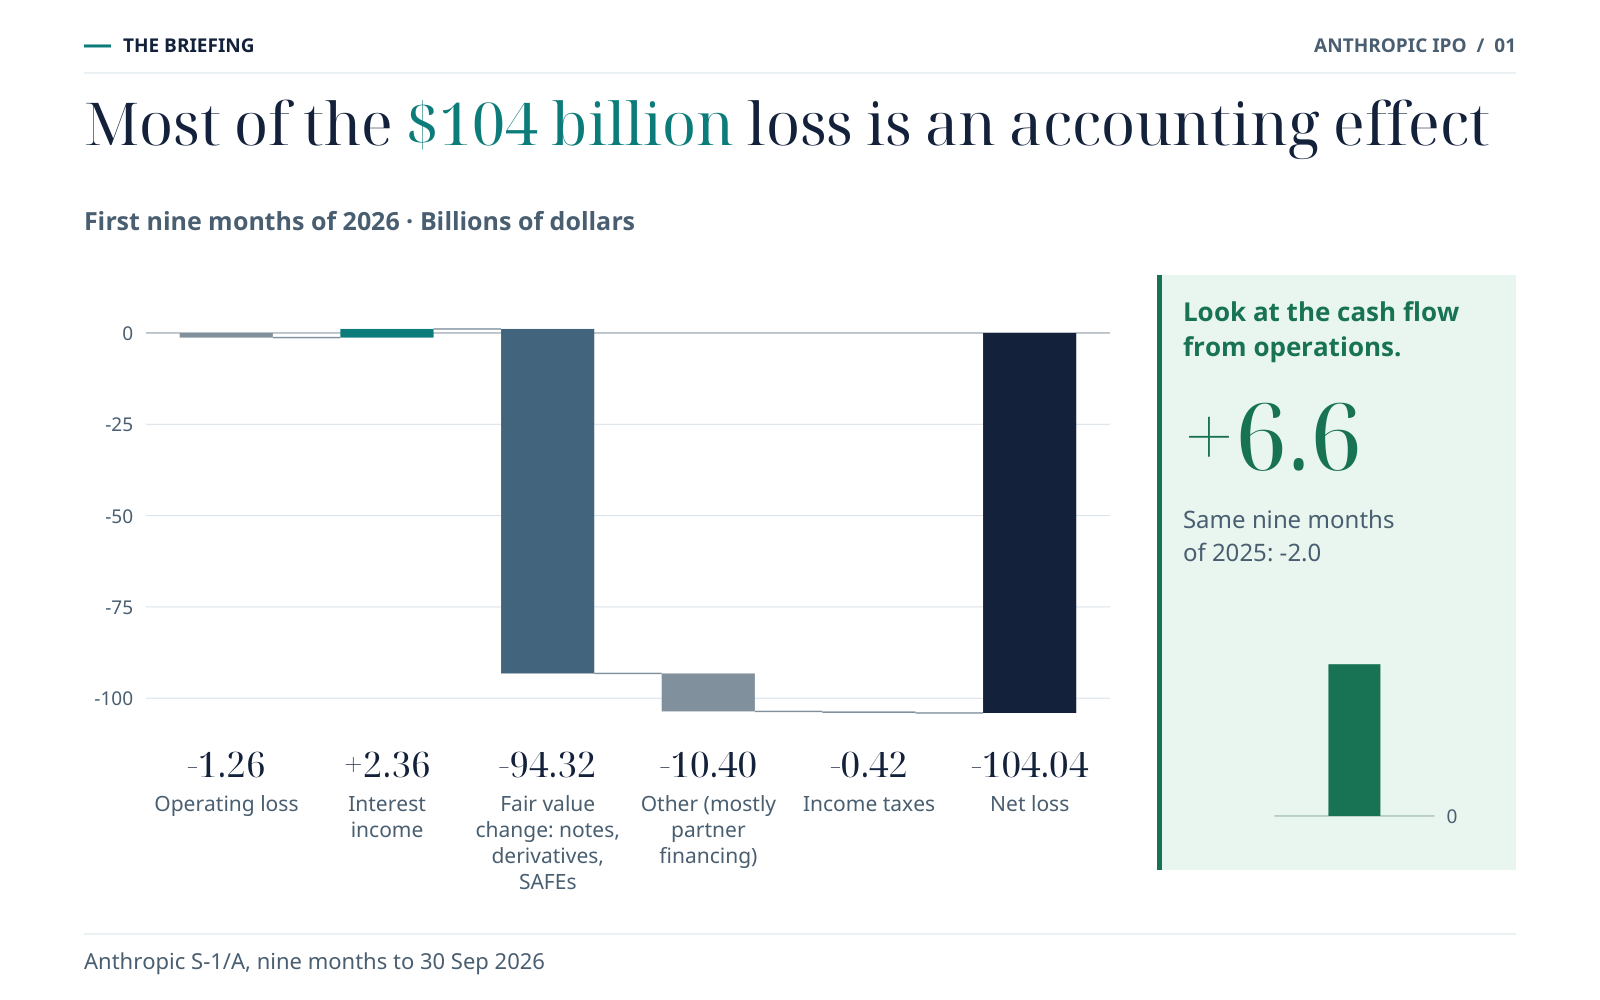
The operating business tells a different story. Its operating loss for the nine months came to $1.26 billion, after an operating profit of $974 million in the second quarter. Cash flow from operations reached $6.6 billion, against an outflow of $2.0 billion a year earlier.
Look at the cash flow from operations. It is the number that is hardest to fake.
The 2026 figures are interim numbers. The first audited full-year figures for 2026 arrive with the annual report.
The fund
Success dilutes: every 50% rise can send 2% more stock to a public benefit fund
846.8M
shares already issued to the fund
2%
more at each 50% step
$124.50
first step after the IPO price
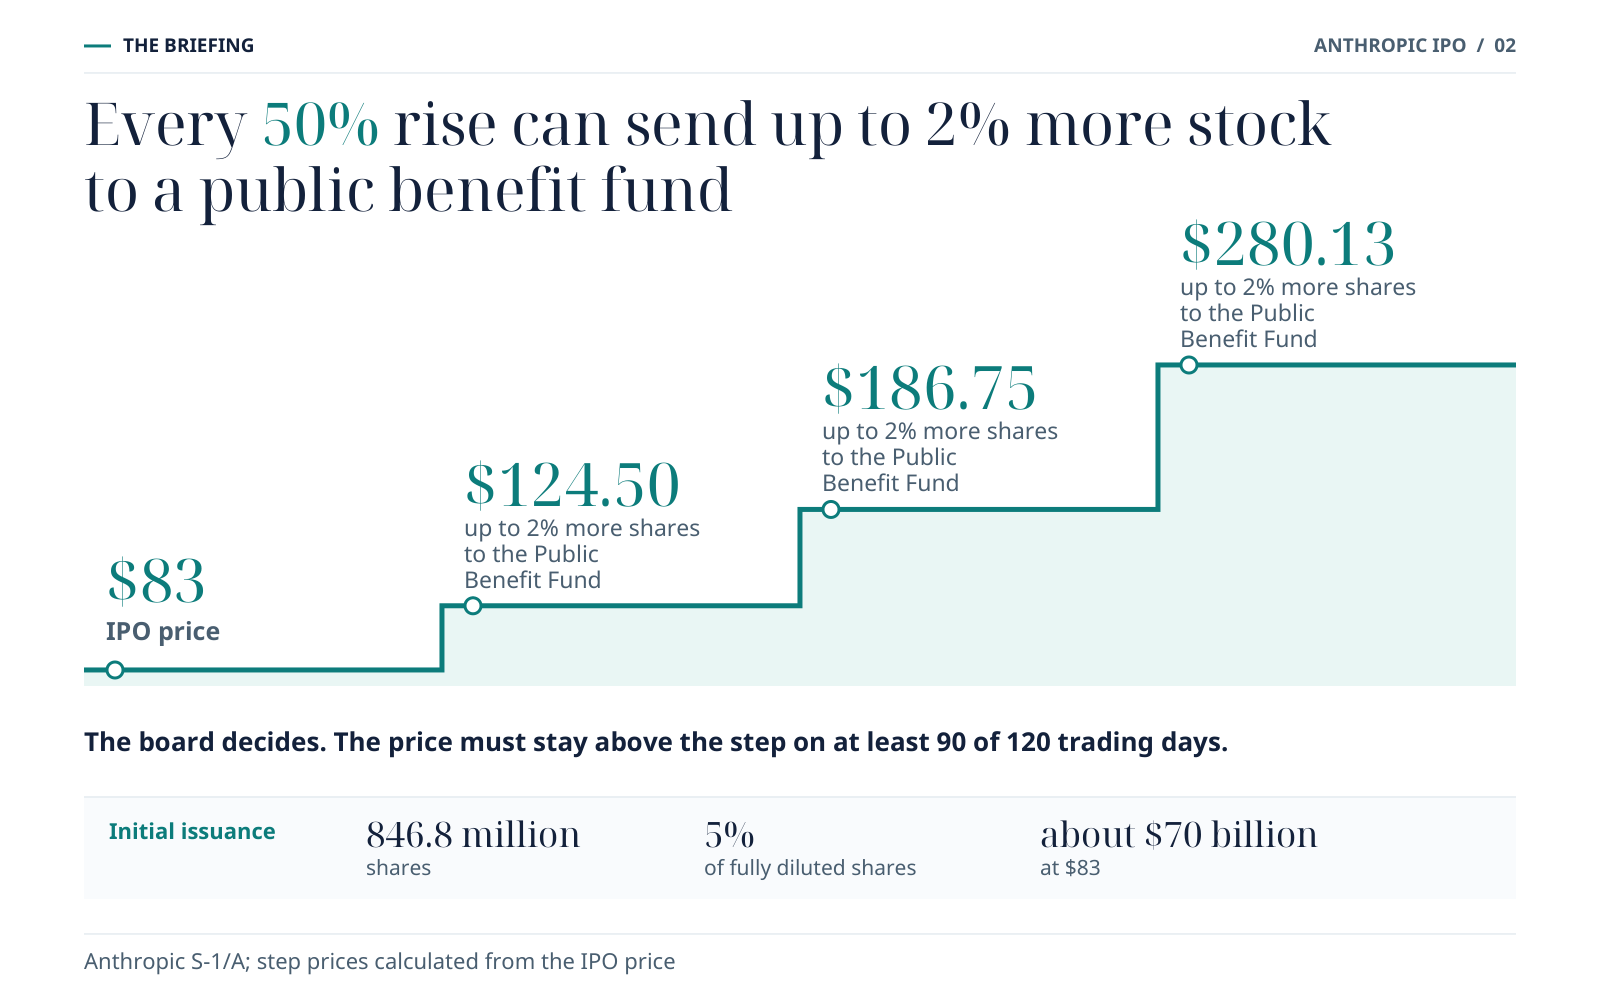
Before the first trade, Anthropic issued 846.8 million Class N shares to the Anthropic Public Benefit Fund, an LLC that Anthropic owns in full. That is 5% of its fully diluted shares as of June 30, 2026. At $83, that stake is worth about $70 billion.
The framework goes further. Each time the share price rises 50% above the previous milestone, the board can decide to issue up to an additional 2% of the outstanding shares to the fund. Counting from the IPO price, the first milestone is $124.50 and the second $186.75. The price must stay above the milestone on at least 90 of 120 trading days, and the average close over the 10 trading days before issuance must also exceed it, before the board can act. A lasting rise in the share price can send part of the gain to the company’s purpose.
A buyer accepts this cost when the vision promises a much larger company. Anthropic’s leadership describes AI that helps build the next generation of AI. In its 10 November amendment, Anthropic stated that it has met the threshold its safety policy sets for AI-accelerated research. It based that call on what it expects from future models.
That ambition is familiar from Nvidia. After reading The Innovator’s Dilemma, Jensen Huang found a way to stay ahead of the competition (Beginner’s Mind EP 163, lesson 3). In my opinion, Anthropic’s founding team embodies a similar vision, and that is promising.
Ambition and caution come in one package at Anthropic. In September, Dario Amodei wrote that AI’s growing ability to build its own next generation is starting to happen across the industry, and that it “must be pursued very carefully, if at all.”
The control
Public buyers get the economics. A trust picks the board.
1 share
elects 4 of 7 directors
50.1%
of the vote in one share
under 50%
of the vote for all public shares together
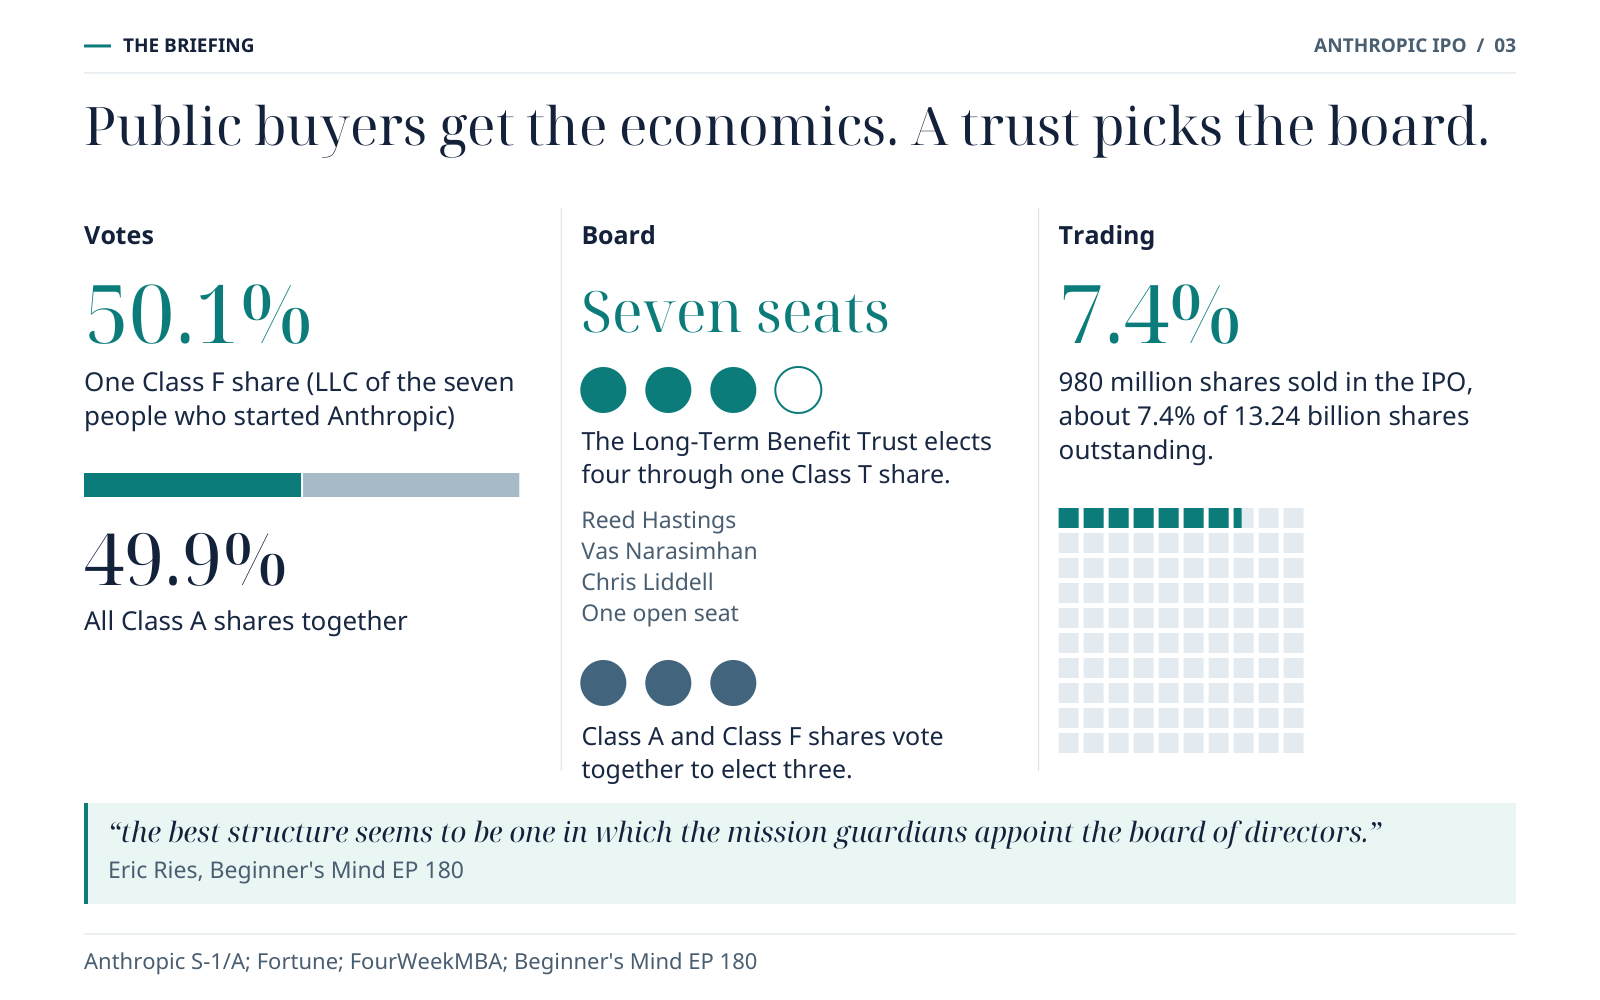
Each share sold today has one vote. Together, the public shares have less than half of the vote. One Class F share, owned by an LLC of the seven people who started Anthropic, has 50.1% of the vote on most matters. One Class T share, owned by the Long-Term Benefit Trust, elects four of the seven board seats. At listing, the trust has filled three of them with Reed Hastings, Vas Narasimhan and Chris Liddell, and the fourth seat is open.
Anthropic is also a public benefit corporation. Its directors must balance the financial interests of stockholders, the best interests of those materially affected by its conduct, and the company’s purpose. The filing states that decisions to “moderate the pace of AI development, delay or restrict the release of models or features, or forgo commercial opportunities” for safety reasons “may not maximize stockholder value.”
Eric Ries, author of Incorruptible, calls this role the mission guardian. In his conversation on Beginner’s Mind, he named Anthropic’s trust as one of the structures that protect a mission.
That’s what they have at Anthropic that’s helped Anthropic navigate these very difficult times.
Eric Ries, author of Incorruptible, on Beginner’s Mind EP 180 Listen at 36:50
His preferred design comes close to Anthropic’s, and he names the benefit:
The best structure seems to be one in which the mission guardians appoint the board of directors.
Eric Ries, author of Incorruptible, on Beginner’s Mind EP 180 Listen at 52:46
Having the trustees, the mission guardians, be a separate body that holds the directors accountable is both better for mission protection, but also frees up the board to be more commercially minded.
Eric Ries, author of Incorruptible, on Beginner’s Mind EP 180 Listen at 49:44
This structure ensures the company sticks to its vision and mission regardless of an ever-changing shareholder base in a public company. That is beneficial as long as they stick to their vision and mission.
There is also a dangerous loophole: what if the mission guardian fails to enforce the mission and has plans of its own?
The question came up in the episode: who guards the mission guardian? Ries answered, “it’s turtles all the way down.” Listen at 53:54. Every role of power has a succession problem, and some structures add a mission protector who keeps the guardians accountable. Patagonia has one.
One detail deserves a closer look. Ries argues that indifference is the wrong trait in a mission guardian and wants people “deeply invested in the outcome.” Anthropic’s trustees are financially disinterested by design. The trust’s policies prohibit them from buying or owning the company’s securities directly. Each trustee receives $400,000 a year in cash, and the chair a further $25,000, an amount that does not depend on profits.
Pharma investors know the model. Ries lists Novo Nordisk, controlled through its foundation, among the companies that kept their mission for generations.
The compute
A $900.9 billion compute bill, and the biggest suppliers own the stock
$900.9B
committed
$70.7B
due within 12 months
~11x
annualized revenue of $81B
Anthropic has committed about $900.9 billion, substantially all of it to compute and infrastructure, with $70.7 billion due in the twelve months after September 30, 2026. That is about 11 times Anthropic’s annualized revenue of about $81 billion at the end of October. The ratio shows scale. Payments stretch out to 2045.
Two of the largest suppliers also own part of the company. Google has a commitment of at least $121.3 billion through July 2033. Amazon has at least $110.0 billion through April 2036. Both own Anthropic stock, with contractual ownership caps of 14.99% and 12%. Their clouds also sell Claude. In the first nine months of 2026, 44% of revenue came through AWS, Google Cloud and Azure.
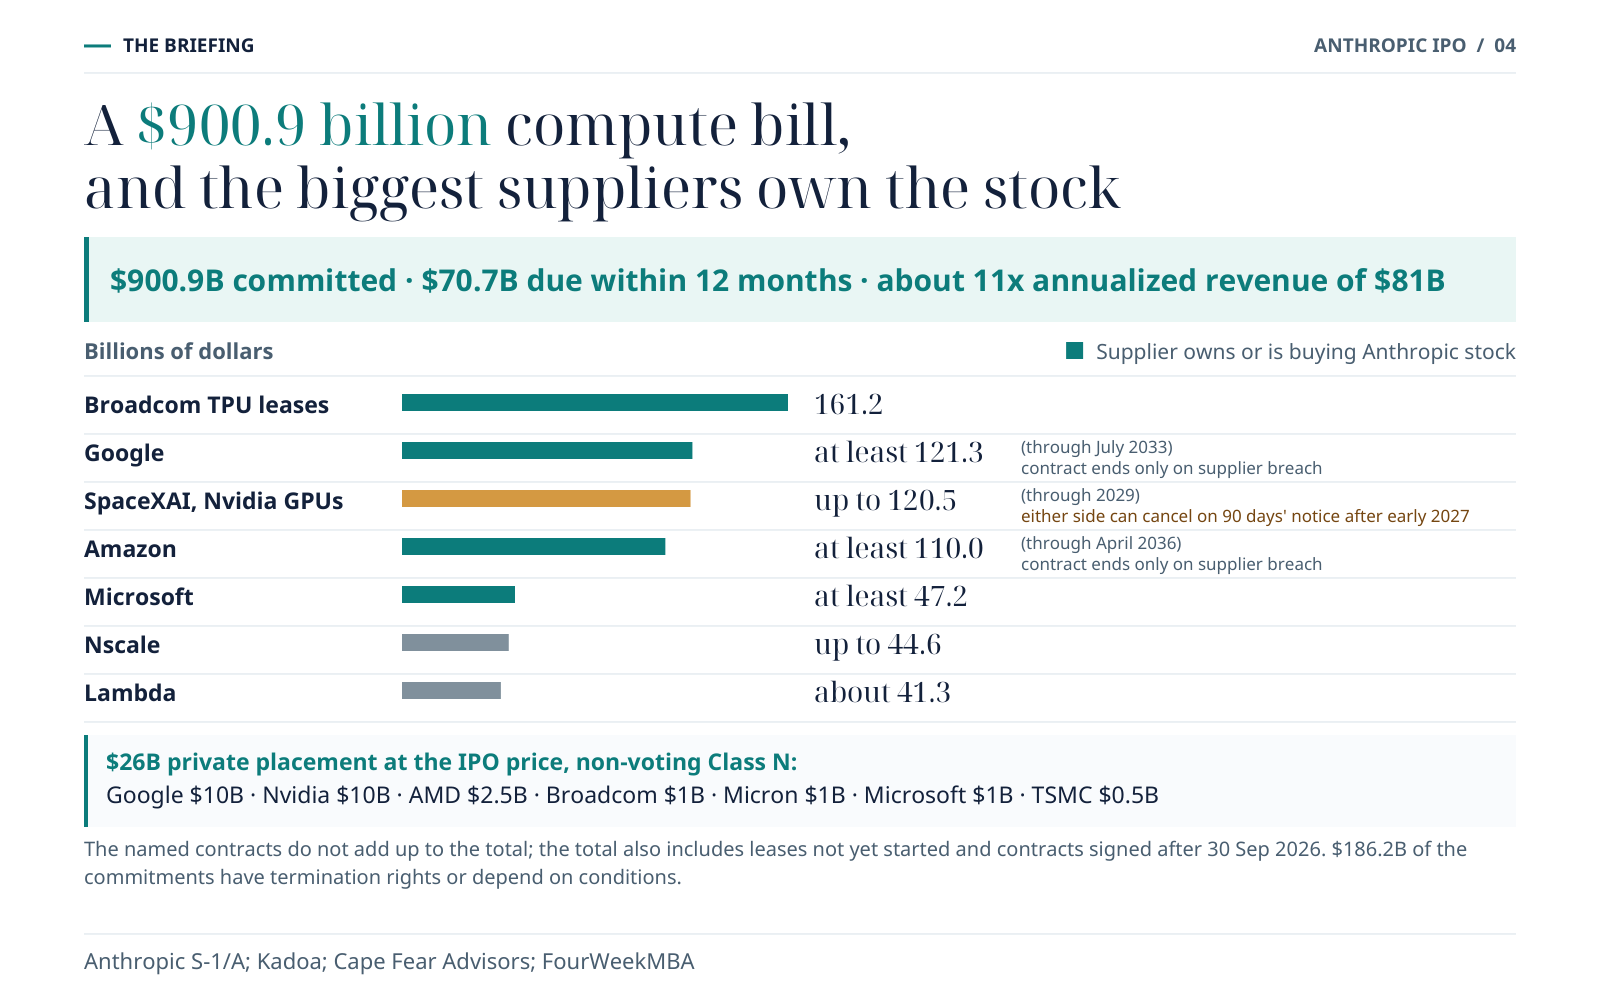
Right after the IPO closes, seven companies are set to buy $26 billion of non-voting Class N stock at the IPO price. Google and Nvidia take $10 billion each, AMD $2.5 billion, Broadcom, Micron and Microsoft $1 billion each, and TSMC $500 million. Broadcom alone leases Anthropic about $161.2 billion of TPU equipment, and Microsoft has a compute commitment of at least $47.2 billion.
That is a relative risk. The biggest suppliers are shareholders at once, and a shareholder that pulls the trigger on Anthropic hurts itself.
The cancellation terms matter as much as the totals. The Google and Amazon contracts last for years, and only a material breach that the supplier fails to fix ends them. The most flexible contracts are with SpaceXAI, which provides compute on Nvidia GPUs. They are worth up to $120.5 billion through 2029. After initial periods that end in January and March 2027, either side can cancel on 90 days’ notice. Across all suppliers, about $186.2 billion of the commitments have termination rights or depend on conditions such as financing or facilities. The 2 November filing still showed $213.8 billion.
According to notes from a meeting with sell-side analysts, Anthropic will not extend the SpaceX contract beyond mid-2027. Neither company has confirmed the remark. For Anthropic, the 90-day exit is a source of flexibility as well as risk. This is the buyer’s side of the sellers’ market in the Nvidia earnings article.
The customers
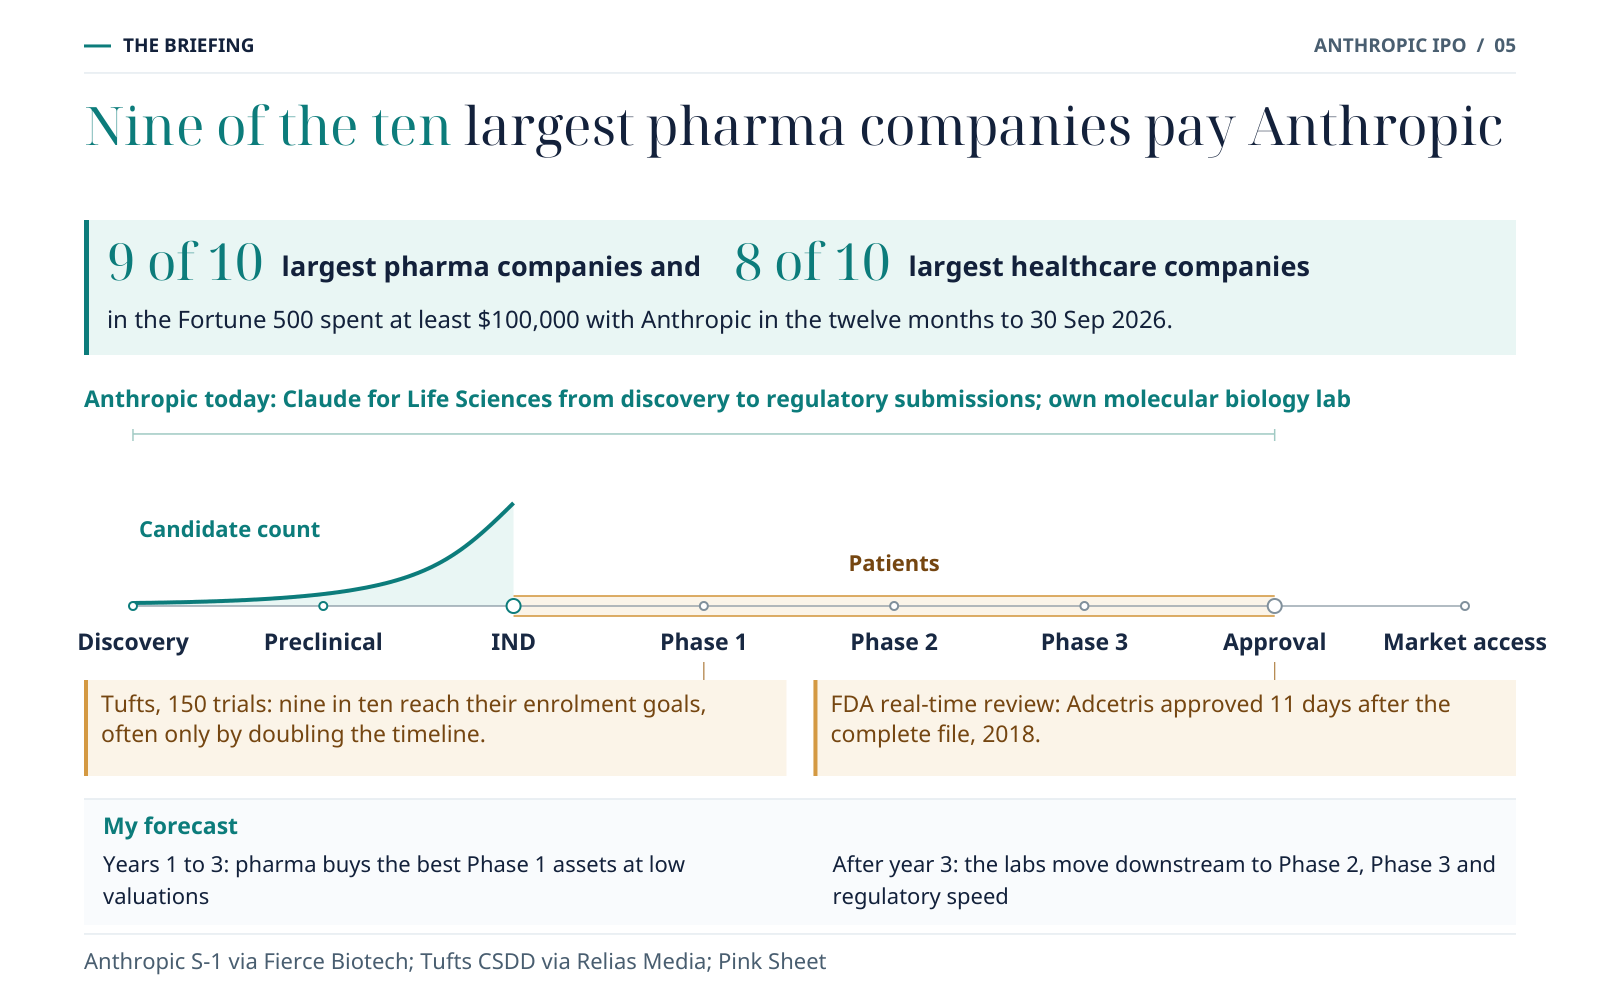
Nine of the ten largest pharma companies pay Anthropic
9 of 10
largest pharma companies in the Fortune 500
8 of 10
largest healthcare companies
Own lab
molecular biology, in-house
That is the most amazing fact in the filing. Anthropic works with pharma, a sector that is hard to get into and lies outside its own tech ecosystem. These are real buyers.
Each of those companies spent at least $100,000 with Anthropic in the twelve months to September 30, 2026. Claude for Life Sciences covers work from early discovery through clinical trial operations and regulatory submissions. Anthropic also has its own drug discovery program on neglected diseases and is building its own molecular biology laboratory. The filing does not state how much the company spends on life sciences. Pharma money also answers part of the question from fact four. The end buyer comes from outside the AI industry, even when the order goes through a cloud marketplace.
Where the next bottleneck lies
The biggest improvement potential is still in clinical trials, and that part gets far less of the labs’ money than discovery. In my opinion, the labs invest massive amounts today in everything before the IND, from ideation to the filing. That is fine, but it also creates many more drug candidates, and I expect a parabolic rise here. Clinical capacity, patient access and market access grow far slower. This will become a buyer’s market and drive the price of preclinical assets down.
Once the frontier labs crash into the bottleneck after the IND, they will have a vital need to accelerate the clinic as well. Why? Because they will feel the pressure. Demis Hassabis and Dario Amodei also need to create shareholder value. What evolutionary pressure will they feel? My guess: solving the clinic, manufacturing and market access.
The remaining bottleneck is access to patients. Every disease at Phase 2 and Phase 3 has a limited pool of compatible patients, and that pool grows far slower than the number of drug candidates. At some point, the value chain will find too few patients for its candidates. Few patients will want to join 12 trials a year, and once a trial delivers a cure, that patient leaves the pool. A Tufts study of 150 trials found that nine in ten reach their enrolment goals, but often only by doubling the original timeline.
What is the last rocket-catch frontier? Simulating the entire biology and its systemic environment.
The way I see it, pharma will have a blast in the next one to three years and pick up the best candidates at low valuations at the Phase 1 stage, with the first human safety data in hand. After three years, the labs’ activity will move downstream to speeding up Phase 2, Phase 3 and the regulatory process. There is a lot of automation potential that is ethical and just and can accelerate the process.
Covid showed what is possible even without automation. The FDA authorized the Pfizer-BioNTech vaccine 11 months after Chinese researchers published the virus’s genetic sequence. Now think of all the summarizing, structuring and report-writing steps that can already happen in parallel with trials, with regulators watching a real-time monitor and data flow. Shouldn’t it be possible at some point for regulators to watch that monitor and, once the last Phase 3 patient is out, schedule their decision meeting for the next day?
The FDA has tested a version of this since 2018. Its Real-Time Oncology Review lets reviewers see key data before the formal submission. In November 2018, the FDA approved a supplemental application for Adcetris 11 days after receiving the complete file.
One more thing
7.4% float, insider sales from day one, index funds in December
Only about 7.4% of the company trades from today. That is 980 million shares out of about 13.2 billion outstanding. Directors, officers and employees outside the founding team can sell up to about 316 million shares from the first day. That equals about a third of the 980 million shares sold in the IPO. Further releases follow on 23 dates over about a year, up to 1.61 billion shares by February 2, 2027.
Then the index funds arrive. Bloomberg reports that Anthropic is on track to join the Nasdaq-100 at the open on December 21. Every fund that tracks the index then buys at the market price, whatever that price is. Nasdaq has not yet confirmed the date.
The supply calendar
-
Day 1 · 19 Nov
Up to about 316 million insider shares can sell, about a third of the 980 million IPO shares
-
Days 27, 48, 62, 76
Further releases for other holder groups
-
21 Dec
Expected Nasdaq-100 entry: index funds buy at the market price (Bloomberg; Nasdaq has not confirmed)
-
2 Feb 2027
Up to 1.61 billion shares released in total
-
Over about a year
23 release dates in all
Two numbers to keep
The first weeks of trading will reflect a small float, steady insider supply and forced index buying. For a long-term investor, two numbers from this filing matter more than the first-day price:
$6.6B
operating cash flow, nine months 2026
9 of 10
largest pharma companies already paying for Claude
Read next: Nvidia Q3 Fiscal 2027 Earnings: Record Revenue, One New Risk and the report Can AI cure every disease by 2036? More news, deals and analysis on The Briefing.
Your Next Move
A decision under uncertainty ahead for your company? Start with one prepared hour on it.
Quick answers
- At what price did Anthropic go public, and when does ANT start trading?
- Anthropic priced 980 million shares at $83 on 18 November 2026, above the marketed range of $70 to $78. The base offering raised about $81.3 billion, and trading on the Nasdaq Global Select Market under the ticker ANT is due to start on 19 November 2026.
- Why did Anthropic report a $104 billion loss?
- About $94.3 billion of the $104.0 billion net loss for the first nine months of 2026 comes from revaluing convertible notes, derivatives and SAFEs at fair value. The operating loss was $1.26 billion, and cash flow from operations was a positive $6.6 billion.
- Who controls Anthropic after the IPO?
- One Class F share, owned by an LLC of the seven people who started Anthropic, has 50.1% of the vote on most matters. One Class T share, owned by the Long-Term Benefit Trust, elects four of the seven directors. All public Class A shares together have less than half of the vote.
- How large are Anthropic’s compute commitments?
- About $900.9 billion, substantially all for compute and infrastructure, with $70.7 billion due in the twelve months after 30 September 2026. About $186.2 billion have termination rights or depend on conditions such as financing or facilities.
- Do pharma companies use Anthropic?
- Yes. Nine of the ten largest pharma companies and eight of the ten largest healthcare companies in the Fortune 500 each spent at least $100,000 with Anthropic in the twelve months to 30 September 2026.
Sources
The offering
Technology.org, pricing and proceeds. technology.org
Anthropic S-1/A No. 2 (SEC). sec.gov
Anthropic S-1/A No. 3 (SEC). sec.gov
01 · The loss and the cash
Kadoa, S-1 financials compiled. kadoa.com
sec-api.io, S-1/A analysis. sec-api.io
02 · The public benefit fund
The Next Web, fund as a wholly owned LLC. thenextweb.com
The Next Web, 10 November threshold determination. thenextweb.com
Dario Amodei, We Must Pace the Frontier. darioamodei.com
Beginner’s Mind EP 163, The NVIDIA Way. buzzsprout.com
03 · Control
Fortune, share structure. fortune.com
Fortune, risk factors. fortune.com
FourWeekMBA, seven-seat board. fourweekmba.com
FourWeekMBA, trustee pay. fourweekmba.com
Beginner’s Mind EP 180 with Eric Ries. buzzsprout.com
04 · Compute
Cape Fear Advisors, SpaceX terms. capefearadvisors.substack.com
Tesla North, analyst remark. teslanorth.com
FourWeekMBA, $26 billion placement. fourweekmba.com
05 · Pharma and the clinic
Fierce Biotech, life sciences in the S-1. fiercehealthcare.com
GEN, life sciences plans. genengnews.com
Relias Media, Tufts enrolment study. reliasmedia.com
Roll Call, Covid vaccine authorization. rollcall.com
FDA, real-time review. fda.gov
Pink Sheet, real-time review approvals. pink.pharmaintelligence.informa.com
Can AI cure every disease by 2036? (report). cslifescienceinvest.com
One more thing · Float and index
FourWeekMBA, float arithmetic. fourweekmba.com
FinanceFeeds, day-one sales. financefeeds.com
TECHi, release calendar. techi.com
StockAnalysis, Nasdaq-100 date. stockanalysis.com
The Briefing
The Briefing. cslifescienceinvest.com
This article is for information only and is not investment advice or a recommendation to buy or sell any security.