Deep Dives › Intuitive Surgical
Company Deep Dive · Life sciences · 31 October 2026
Intuitive Surgical: price for adoption in robotic surgery
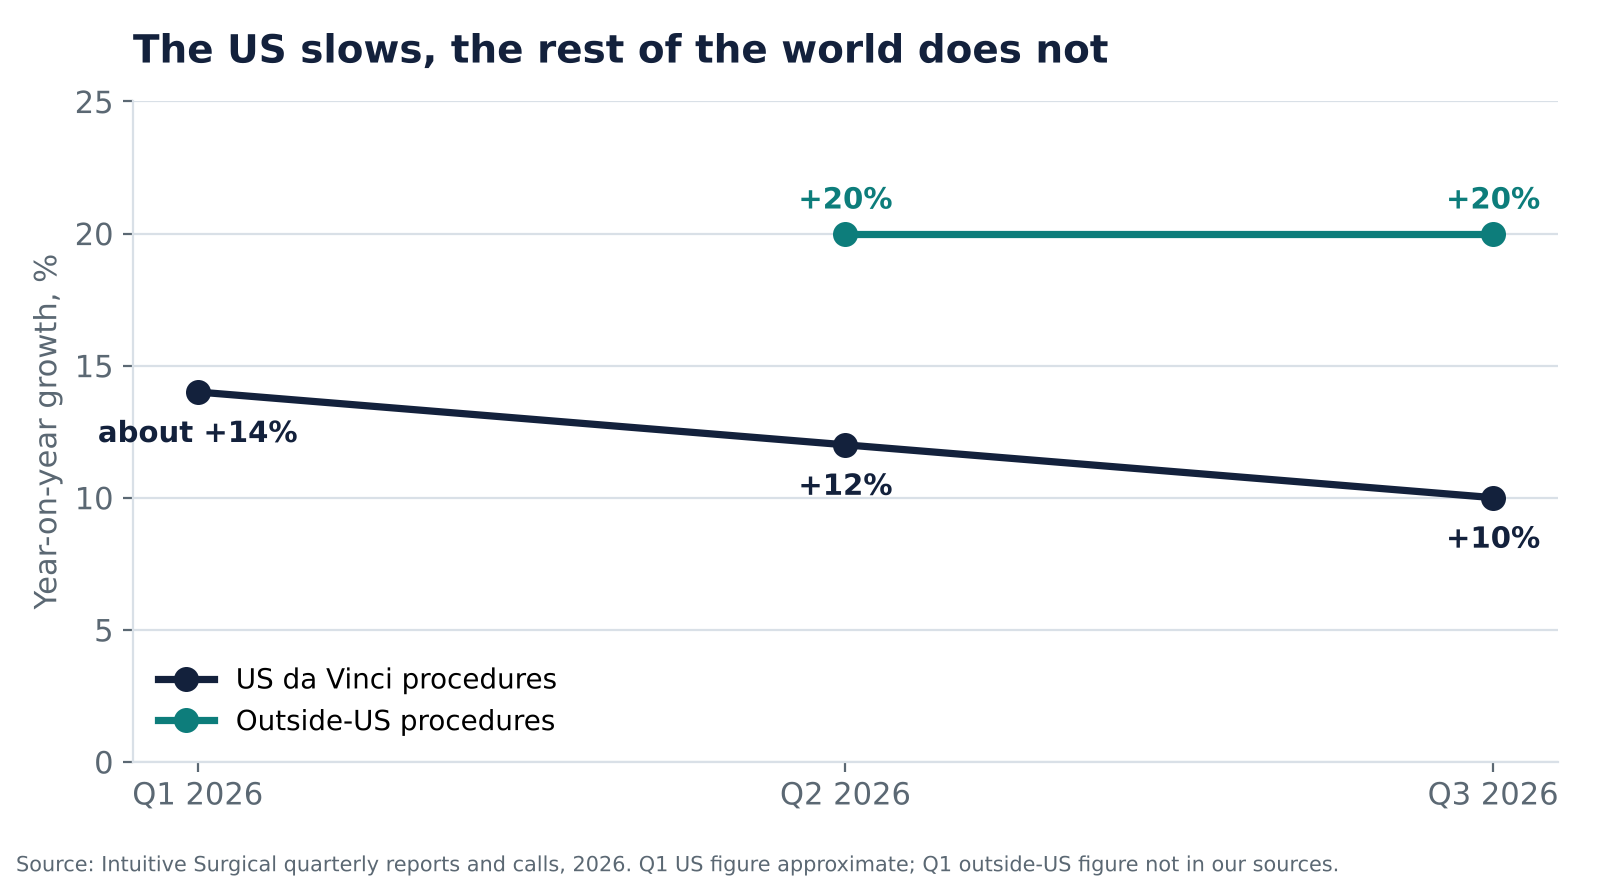
Intuitive Surgical owns the reference system in soft-tissue robotic surgery. In the third quarter of 2026 it beat on every reported line, yet US procedure growth slowed for a third straight quarter and management announced the first deliberate cut to revenue per procedure since 2020. The quality of the business is settled. The next eighteen months decide whether price can buy volume before Johnson & Johnson, Medtronic and a Stryker-backed CMR Surgical reach the same operating theatres.
By Christian Soschner, 26 years building companies
Key facts
- 12,094 da Vinci systems installed, up 12% year on year.
- Q3 2026 revenue of $3.05 billion, up 22%; instruments and accessories $1.80 billion, up 18%.
- US procedures +10% against +20% outside the US.
- Instrument revenue per procedure guided down 3 to 5% by the end of 2027.
- $450 million settlement of a class action over third-party instruments and servicing, without admission of wrongdoing.
- Three funded, cleared rivals in the US: J&J Ottava, Medtronic Hugo and CMR Versius, now sold through Stryker.
The big picture: physical AI enters the operating theatre
Surgical robotics belongs to Physical AI: machine intelligence that acts in the physical world. The economics of robotics tend to accrue to the enabling layer, the installed base, the controls and the data, and Intuitive is the clearest listed example of that layer. Its paying customer is the hospital, whose budget does not depend on hyperscaler spending. The binding constraints are hospital financing, clinical evidence on cost per case, and the regulatory calendar.
MarketsandMarkets puts the surgical robots market, including instruments and services, at $13.7 billion in 2025 and about $27 billion by 2030. On that definition, Intuitive’s revenue of about $12 billion a year already equals most of today’s market. That is the position the new rivals are attacking.
The leadership question
When do you trade margin for installed base, and how do you prove the trade worked?
Intuitive faces that question with 12,094 systems in the field. A scale-up faces the same question with its first fifty.
What to watch
- Late January 2027: the Q4 report and 2027 outlook. US growth back to 11% and procedures of 13% or more would confirm the price-for-adoption bet.
- First half of 2027: US clearance of the expanded Extended Use Program, the first test of volume elasticity.
- 2027: court approval of the $450 million settlement and its injunctive terms.
- Ongoing: how broadly J&J launches Ottava, Stryker’s option on CMR, and new indications for Medtronic Hugo.
- First half of 2028: expected telesurgery clearances.
Read the full deep dive
The full analysis covers the business model and moat, a board-level read of the leadership team, three business scenarios to 2030, where our analyses disagree, and a pre-mortem.
Your Next Move
Leading a company through a decision like this one? Your Next Move: Executive Advisory Session gives you an experienced outside view on the one decision in front of you, in three steps.
See Your Next MoveThis analysis is for information only and is not investment advice or a recommendation to buy or sell any security. The author may hold positions in the companies discussed.